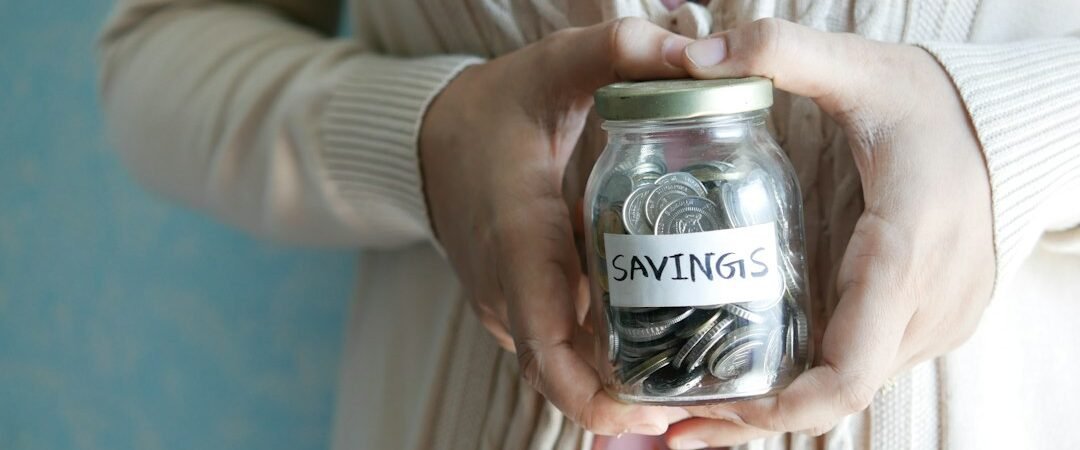
An emergency fund is money set aside for unexpected costs such as a car repair, urgent travel, a medical bill, or a temporary loss of income. Saving can feel difficult when rent, groceries, and debt payments already consume most of a paycheck. The answer is to begin with a manageable target and build a repeatable habit rather than waiting until you can save a large amount.
Choose a first milestone
Start with a small goal that would cover one realistic surprise in your life. For one household, that might be a basic car repair; for another, it could be a utility bill or urgent prescription. Once you reach the first milestone, build toward a larger cushion based on essential monthly expenses, income stability, dependents, and insurance coverage.
Find a sustainable amount
Review one month of spending and identify a savings amount you can repeat without missing essential bills. Even a modest transfer each payday can help. If your income varies, consider a small baseline transfer plus an additional amount in higher-income weeks. Pause or reduce transfers if saving would cause overdrafts or force you to use expensive credit for essentials.
Make saving automatic—but flexible
- Set a recurring transfer soon after payday, when the money is available.
- Use a separate, accessible savings account so the balance is easy to identify.
- Enable low-balance alerts on your spending account to reduce overdraft risk.
- Direct part of occasional refunds, gifts, or extra income to the fund when practical.
Choose the right place for the money
Emergency savings should be relatively safe and accessible. Compare account fees, minimum balances, withdrawal rules, and deposit insurance. Avoid putting money you may need soon into volatile investments or locking it away where access is difficult. The highest advertised rate is not the only factor; reliability and clear terms matter too.
Decide what counts as an emergency
Write down examples of legitimate uses before the pressure arrives. A necessary repair or unexpected medical cost may qualify, while a planned holiday generally belongs in a separate savings goal. If you use the fund, avoid guilt: its purpose is to help absorb shocks. Make a plan to rebuild it when your budget allows.
Balance savings and debt
High-interest debt can be expensive, but having no cash cushion can cause a small surprise to become new debt. A starter emergency reserve may help you avoid that cycle while you follow a realistic debt plan. The right balance depends on interest rates, minimum payments, income stability, and urgent obligations.
For consumer budgeting guidance, see the Consumer Financial Protection Bureau’s savings resources. The most useful emergency fund is one you can keep building without destabilizing the rest of your finances.
This is general educational information, not individualized financial advice.